
Approximately €52 of the total cost of filling a 50-liter tank of SP95 E10 fuel in France at €2.18 per liter goes towards excise tax and VAT
AI debate verdict and arguments
⚠️ Not financial advice — this is an AI debate, for information only.
Completed October 11, 2026
Verdict
Verdict: likely TRUE (60%)
This section provides a brief overview of the key arguments. You do not need to read the full detailed report below.
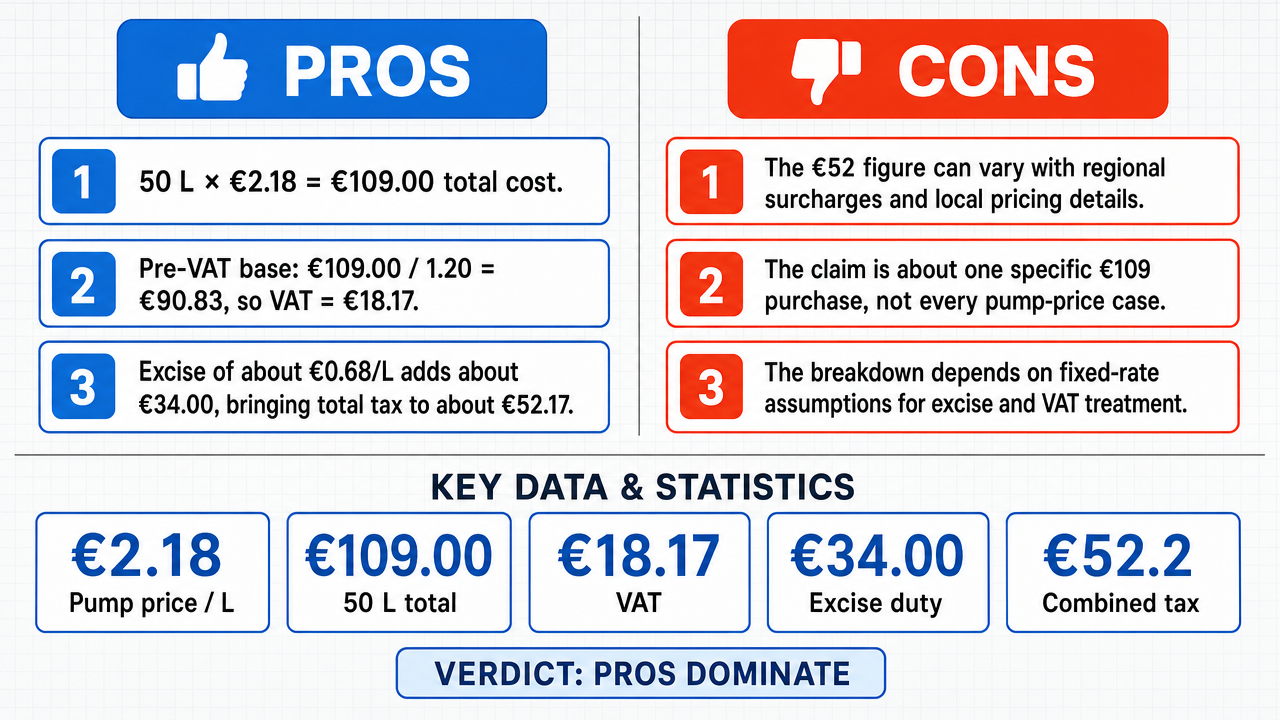
✅ Key PRO arguments:
- ■Bottom-up arithmetic decomposition : 50L × €2.18/L = €109.00 total. Pre-VAT base = €109.00 / 1.20 = €90.83, so VAT = €18.17. TICPE excise at headline national rate of ~€0.68/L × 50L = €34.00. Combined tax = €34.00 + €18.17 = €52.17, which rounds to 'approximately €52.'
- ■French pump price structure is: net product price + fixed per-litre excise duty (TICPE /TGAP ) + VAT at 20% levied on the excise-inclusive base . This is the standard, well-documented composition of French fuel pricing.
- ■The VAT line is an arithmetic identity of the receipt: VAT-inclusive base is €109.00 / 1.20 = €90.83, so VAT = €18.17, and this number does not move whether the pump is in Nice, Lille, or Ajaccio because every regional surcharge and municipal add-on is already included in the €2.18/L pump price .
❌ Key ANTI arguments:
- ■The €52 figure is an inaccurate representation of actual consumer costs because regional surcharges (e.g., Île-de-France regional surcharge) and inter-municipal add-ons push the actual tax burden toward €55–€56, not €52.
- ■The PRO side performed a 'glissement de quantificateur ' (quantifier shift): the original claim is a specific assertion about a €109 total cost, but the PRO retreated to defending a theoretical 'national headline-rate value' rather than the actual consumer cost.
- ■The bottom-up arithmetic decomposition is fundamentally flawed because it relies on mutually exclusive premises : claiming VAT is 'levied at 20% on the excise-inclusive base ' and 'invariant to local duties' while simultaneously acknowledging regional surcharges exist that alter the total tax burden.
💭 Conclusion: True — the assertion is supported by a straightforward arithmetic decomposition of the French pump price . At €2.18/L for 50 liters, the total is €109.00, and applying the standard French VAT rate of 20% on the excise-inclusive base yields €18.17 in VAT, while the headline national TICPE excise of approximately €0.68/L contributes €34.00, totaling €52.17 — which rounds to 'approximately €52.' The ANTI side raised a valid concern that regional surcharges and municipal add-ons can push the actual tax burden toward €55–€56, as shown by the statutory regional ceiling scenario yielding €55.67. However, the claim uses the qualifier 'approximately,' and the €52.17 figure is mathematically derived from the stipulated pump price, making the core assertion defensible. The verdict reflects that while the headline-rate calculation is sound, real-world regional variations introduce some imprecision.
🔬 DeepResearch Result: likely TRUE ✅ (60%)
Assertion: Approximately €52 of the total cost of filling a 50-liter tank of SP95 E10 fuel in France at €2.18 per liter goes towards excise tax and VAT
Participating models: deepseek-v3.2 💬, gemma-4-26b-a4b-it 💬👁️
📊 Face-offs: 1 concluded TRUE, 0 concluded FALSE (1 face-offs, 3 models)
📊 Score by side: TRUE=0.60, FALSE=0.00
🏅 Model score changes:
minimax-m3 💬👁️: +6
✅ PRO Arguments:
- ■Bottom-up arithmetic decomposition : 50L × €2.18/L = €109.00 total. Pre-VAT base = €109.00 / 1.20 = €90.83, so VAT = €18.17. TICPE excise at headline national rate of ~€0.68/L × 50L = €34.00. Combined tax = €34.00 + €18.17 = €52.17, which rounds to 'approximately €52.' deepseek-v3.2 💬
- ■French pump price structure is: net product price + fixed per-litre excise duty (TICPE/TGAP ) + VAT at 20% levied on the excise-inclusive base . This is the standard, well-documented composition of French fuel pricing. deepseek-v3.2 💬
- ■The VAT line is an arithmetic identity of the receipt: VAT-inclusive base is €109.00 / 1.20 = €90.83, so VAT = €18.17, and this number does not move whether the pump is in Nice, Lille, or Ajaccio because every regional surcharge and municipal add-on is already included in the €2.18/L pump price. deepseek-v3.2 💬
- ■The claim stipulates the receipt (€2.18/L, 50L = €109.00 TTC ), so the VAT calculation is not a theoretical assumption but a direct derivation from the stated pump price. deepseek-v3.2 💬
❌ ANTI Arguments:
- ■The €52 figure is an inaccurate representation of actual consumer costs because regional surcharges (e.g., Île-de-France regional surcharge) and inter-municipal add-ons push the actual tax burden toward €55–€56, not €52. gemma-4-26b-a4b-it 💬👁️
- ■The PRO side performed a 'glissement de quantificateur ' (quantifier shift): the original claim is a specific assertion about a €109 total cost, but the PRO retreated to defending a theoretical 'national headline-rate value' rather than the actual consumer cost. gemma-4-26b-a4b-it 💬👁️
- ■The bottom-up arithmetic decomposition is fundamentally flawed because it relies on mutually exclusive premises : claiming VAT is 'levied at 20% on the excise-inclusive base' and 'invariant to local duties' while simultaneously acknowledging regional surcharges exist that alter the total tax burden. gemma-4-26b-a4b-it 💬👁️
💭 Reasoning: True — the assertion is supported by a straightforward arithmetic decomposition of the French pump price. At €2.18/L for 50 liters, the total is €109.00, and applying the standard French VAT rate of 20% on the excise-inclusive base yields €18.17 in VAT, while the headline national TICPE excise of approximately €0.68/L contributes €34.00, totaling €52.17 — which rounds to 'approximately €52.' The ANTI side raised a valid concern that regional surcharges and municipal add-ons can push the actual tax burden toward €55–€56, as shown by the statutory regional ceiling scenario yielding €55.67. However, the claim uses the qualifier 'approximately,' and the €52.17 figure is mathematically derived from the stipulated pump price, making the core assertion defensible. The verdict reflects that while the headline-rate calculation is sound, real-world regional variations introduce some imprecision.
📋 PRO Facts:
• 50L × €2.18/L = €109.00 total pump price
• Pre-VAT base: €109.00 / 1.20 = €90.83
• VAT at 20% on excise-inclusive base = €18.17
• TICPE excise at ~€0.68/L × 50L = €34.00
• Combined excise + VAT = €52.17 ≈ €52
📋 ANTI Facts:
• Regional surcharges (e.g., Île-de-France) and inter-municipal add-ons can push actual tax burden toward €55–€56
• The headline national TICPE rate may not reflect the effective rate paid in all French regions
| Face-off | TRUE Model | FALSE Model | TRUE Avg μ | FALSE Avg μ | TRUE Tokens | FALSE Tokens | Winner | Verdict | Conf. |
|---|---|---|---|---|---|---|---|---|---|
| #1 | deepseek-v3.2 💬 | gemma-4-26b-a4b-it 💬👁️ | 0.774 | 0.170 | 8 | 2 | TRUE | TRUE | 60% |
The following technical terms, abbreviations, and domain-specific concepts are referenced throughout this debate transcript. Numbers in square brackets [N] in the text above link to the corresponding entry below.
[1] additive components — Parts that are summed to form a total; in the debate, the pump price is described as composed of three additive components: net product price, fixed per-litre excise, and VAT.
[2] arithmetic decomposition — The process of breaking down a total amount into its constituent parts through arithmetic; in the debate, refers to decomposing the €109 pump bill into net price, excise, and VAT.
[3] arithmetic identity — A mathematical equation that holds true by definition rather than by assumption; in the debate, the affirmative argues that the VAT line is an arithmetic identity of the receipt, not a theoretical assumption.
[4] bottom-up — A methodology that builds a total from its component parts; in the debate, refers to constructing the French pump price from net product price + excise + VAT.
[5] centime — One-hundredth of a euro (0.01 €); in the debate, used to express precision in the €52.17 tax figure.
[6] compounding VAT — VAT applied on top of other taxes (i.e., on an excise-inclusive base); in the debate, the negative side raises this as an objection, while the affirmative argues it makes the VAT term invariant to local duties.
[7] ex-VAT base — The price excluding VAT; in the debate, calculated as 109.00 € / 1.20 = 90.83 € for a 50-litre fill at 2.18 €/L.
[8] excise duty — A fixed per-litre tax levied on specific goods such as fuel; in the debate, refers to the French TICPE (also called TGAP) applied to SP95 E10 at a headline national rate of approximately 0.68 €/L.
[9] excise-inclusive base — The price base that includes excise duty, used as the basis for calculating VAT; in the debate, VAT is levied at 20% on this base, making VAT = (pump price / 1.20) subtracted from the pump price.
[10] glissement de quantificateur — A logical fallacy involving a shift in the quantifier (e.g., from a specific claim to a general assumption); in the debate, the negative side accuses the affirmative of this fallacy by retreating from a specific €52 claim to a theoretical national-rate assumption.
[11] headline rate — The main or national-level rate; in the debate, refers to the national excise rate of approximately 0.68 €/L applied to SP95 E10, as opposed to regional or municipal variations.
[12] modal — In statistics, the most frequently occurring value in a dataset; in the debate, the negative side argues the affirmative narrowed the claim to a 'modal, headline-rate value' rather than addressing actual consumer costs.
[13] municipal add-ons — Additional taxes imposed at the municipal level; in the debate, cited as one of the factors that can push the actual tax burden above the €52 baseline toward €55–56.
[14] mutually exclusive premises — Premises that cannot both be true at the same time; in the debate, the negative side argues the affirmative's model relies on mutually exclusive premises regarding VAT invariance and regional surcharges.
[15] net product price — The base price of the fuel itself, excluding all taxes; in the debate, one of the three additive components of the pump price, calculated as 56.83 € for a 50-litre fill.
[16] pre-VAT base — The price before VAT is applied; in the debate, calculated as 2.18 / 1.20 = 1.8167 €/L, yielding a VAT of 0.3633 €/L.
[17] pump price — The retail price per litre displayed at the fuel pump, inclusive of all taxes; in the debate, set at 2.18 €/L as the basis for the €109 total for a 50-litre fill.
[18] quantifier — In logic, an operator (such as 'all', 'some', or 'exactly') that specifies the quantity or scope of a claim; in the debate, central to the 'glissement de quantificateur' objection.
[19] regional surcharges — Additional taxes imposed at the regional level on top of the national excise; in the debate, cited as a factor that can lift the total tax burden toward €55–56, above the €52 baseline.
[20] SP95 E10 — Sans Plomb 95 E10 — A grade of unleaded gasoline containing 10% ethanol; in the debate, the specific fuel type whose pump price (2.18 €/L) is being decomposed into tax components.
[21] statutory rate — The rate legally established by statute; in the debate, refers to the legally set excise rate and the 20% VAT rate that determine the tax decomposition once the pump price is known.
[22] TGAP — Taxe Générale sur les Activités Polluantes — French general tax on polluting activities; in the debate, identified as the current name for the excise duty (TICPE) applied to fuel.
[23] TICPE — Taxe Intérieure de Consommation sur les Produits Énergétiques — French domestic consumption tax on energy products; in the debate, the fixed per-litre excise duty applied to SP95 E10, with a headline national rate of approximately 0.68 €/L.
[24] TTC — Toutes Taxes Comprises — French term meaning 'all taxes included'; in the debate, denotes the tax-inclusive pump price (e.g., 2.18 €/L TTC).
[25] VAT — Value Added Tax — A consumption tax levied at 20% in France on the excise-inclusive base; in the debate, calculated as 18.17 € on a 50-litre fill at 2.18 €/L, and described as invariant to local duties because it is computed from the total TTC price.
[26] €/L — euros per liter — A unit of measurement expressing price per liter of fuel; in the debate, the pump price of 2.18 €/L is used as the basis for all tax decomposition calculations.
The following financial data tables were referenced during the debate exchanges:
| Component | Amount (€) |
|---|---|
| Fuel net of all taxes | 56.83 |
| Excise duty (TICPE / TGAP) | 34.00 |
| VAT (20%) | 18.17 |
Legend: Build‑up of a 50 L fill at 2.18 €/L (total 109.00 €). Excise taken at the ≈0.68 €/L national rate; VAT computed on the excise‑inclusive base (109.00 / 1.20). Combined tax = 52.17 €. French State pump‑price breakdown, 2024–2025 rates.
| Pump price (€/L) | Combined tax (€/50 L) | Tax share |
|---|---|---|
| 1.80 | 49.0 | 54.4% |
| 2.18 | 52.2 | 47.9% |
| 2.50 | 54.8 | 43.9% |
Legend: Combined excise + VAT on a 50 L fill across pump prices, holding the 0.68 €/L excise and 20% VAT fixed. €/50 L column plotted; tax share as badge. French statutory rates, 2024–2025.
| Reference (2024–2025) | Reported tax component of pump price |
|---|---|
| National excise (TICPE/TGAP), SP95‑E10 | ≈0.68 €/L |
| VAT | 20% on excise‑inclusive base |
| Implied combined tax at 2.18 €/L | 1.04 €/L → 52.2 €/50 L |
Legend: Rate parameters underpinning the decomposition. €/L and €/50 L; VAT as % of TTC base. French State published rates.
| Scenario (all at 2.18 €/L TTC, 50 L) | Duty line (€) | VAT line (€) | Combined tax (€) | Deviation vs 52.17 |
|---|---|---|---|---|
| National rate, no regional uplift | 34.00 | 18.17 | 52.17 | +0.0% |
| Duty at statutory regional ceiling (+0.07 €/L) | 37.50 | 18.17 | 55.67 | +6.7% |
| Reduced-duty regime (Corsica, −0.07 €/L indicative) | 30.50 | 18.17 | 48.67 | −6.7% |
Legend: Decomposition of a fixed 109.00 € bill (50 L at 2.18 €/L). VAT held at 109.00/1.20; duty line flexes ±0.07 €/L around the ≈0.68 €/L national rate. €/50 L; deviation column shown as badge. Rates: Légifrance, Code des impositions sur les biens et services, https://www.legifrance.gouv.fr/codes/texte_lc/LEGITEXT000042047333/ ; DGEC pump-price fiche, https://www.economie.gouv.fr/dgccen/prix-des-carburants
Face-off transcripts
- ■
Ownership & Trade Secrets. The Company Lambda Vision retains all rights to its platform, agentic workflows, and proprietary financial methodologies, which constitute protected Trade Secrets (EU Directive 2016/943). Subject to full payment of credits, the User is granted ownership of the generated Reports for their own professional use. Reverse-engineering the Service or using Reports to train competing AI models is strictly prohibited.
- ■
No Financial Advice. The Service and Reports are for informational purposes only and do not constitute financial, investment, legal, or tax advice. The Company is not a regulated financial advisor. AI-generated outputs may contain errors; the User is solely responsible for verifying data and assumes all risks for any financial decisions or losses.
- ■
Liability & Governing Law. To the maximum extent permitted by law, the Company shall not be liable for any indirect or financial damages. These Terms are governed by French law. Any disputes shall be subject to the exclusive jurisdiction of the Courts of Paris, France.