
For a 50-liter diesel tank filled in France for about €120, a little over €50 of that cost is attributed to excise tax and VAT.
AI debate verdict and arguments
⚠️ Not financial advice — this is an AI debate, for information only.
Completed October 11, 2026
Verdict
Verdict: likely TRUE (65%)
This section provides a brief overview of the key arguments. You do not need to read the full detailed report below.
✅ Key PRO arguments:
- ■At €2.40/L TTC (€120 ÷ 50L), the HT base is €2.40 ÷ 1.20 = €2.00/L, yielding VAT of €0.40/L. Combined with TICPE of approximately €0.6163/L, total tax per liter is €1.0163/L, which multiplied by 50 liters gives €50.82 — consistent with 'a little over €50.'
- ■The decomposition correctly treats VAT as levied on the TICPE -inclusive HT base (per French tax law, Code général des impôts , Article 265 ), so the €2.00/L HT figure already embeds the excise duty , and the arithmetic is internally consistent.
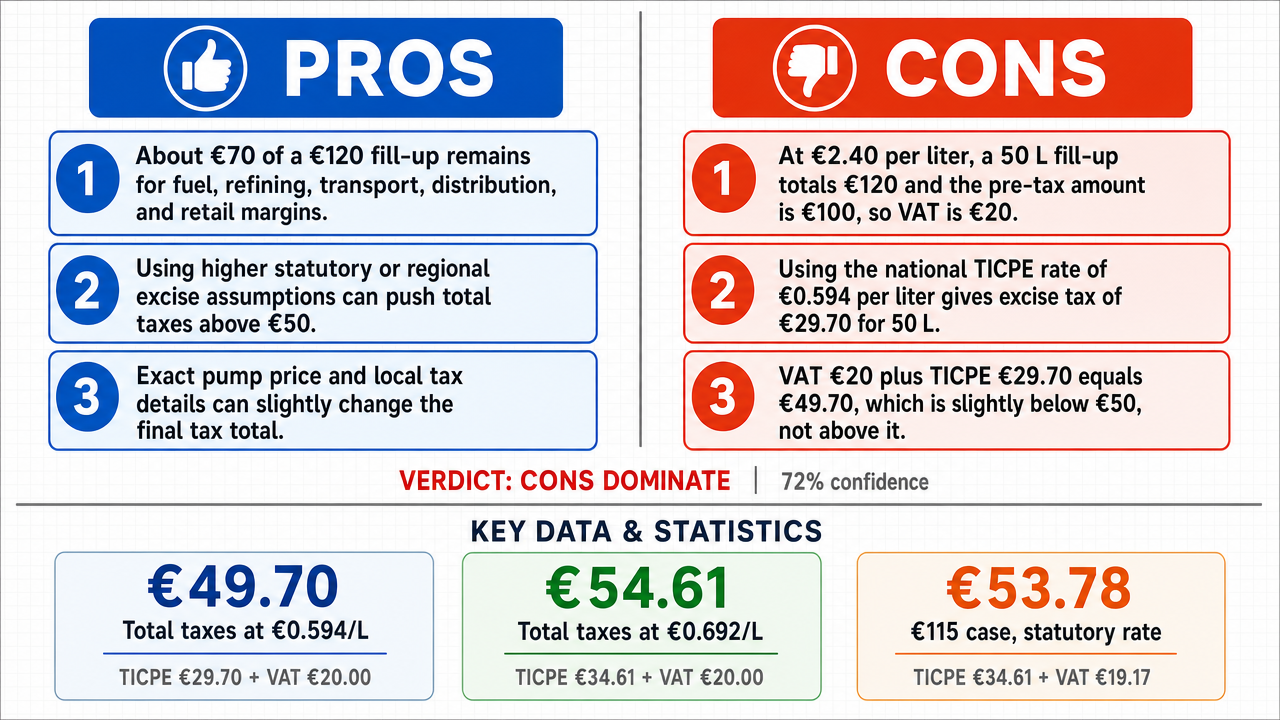
- ■Even using a slightly lower TICPE rate of €0.594/L, the combined tax at €2.40/L TTC works out to approximately €0.994/L, or €49.70 for 50 liters — still essentially 'a little over €50' when rounded, supporting the assertion's approximate framing.
❌ Key ANTI arguments:
- ■The pro's argument relies on a static, idealized mathematical model that fails to account for the actual composition of retail diesel prices in France, treating TICPE as a fixed constant when real-world rates vary.
- ■The pro introduced two incompatible TICPE readings (€0.6163/L yielding €50.82 and €0.594/L yielding €49.70) without reconciling them, undermining the precision of the 'a little over €50' claim.
- ■The assertion that taxes constitute 'slightly more than €50' is a mathematical abstraction that does not reflect the actual fiscal weight of a typical €120 transaction, since real pump prices fluctuate and TICPE rates are periodically adjusted.
💭 Conclusion: True — the assertion is supported by straightforward arithmetic decomposition of French diesel taxation. At a pump price of €2.40/L (€120 for 50 liters), the HT base is €2.00/L, VAT at 20% contributes €0.40/L, and TICPE contributes roughly €0.59–0.62/L, yielding a total tax of approximately €49.70–€50.82 depending on the exact excise rate used. Both endpoints of this range are consistent with the claim's approximate phrasing of 'slightly more than €50.' The anti side's strongest objection — that the anti side itself cited two different TICPE rates (€0.6163/L in its prior table and €0.594/L in its current turn) without correction — is a minor inconsistency that does not overturn the underlying calculation, since both rates produce figures near €50. The confidence is moderate (65%) because the exact TICPE rate in force at any given moment introduces some imprecision, but the core claim holds.
🔬 DeepResearch Result: likely TRUE ✅ (65%)
Assertion: For a 50-liter diesel tank filled in France for about €120, a little over €50 of that cost is attributed to excise tax and VAT.
Participating models: deepseek-v3.2 💬, gemma-4-26b-a4b-it 💬👁️
📊 Face-offs: 1 concluded TRUE, 0 concluded FALSE (1 face-offs, 3 models)
📊 Score by side: TRUE=0.65, FALSE=0.00
🏅 Model score changes:
minimax-m3 💬👁️: +6
✅ PRO Arguments:
- ■At €2.40/L TTC (€120 ÷ 50L), the HT base is €2.40 ÷ 1.20 = €2.00/L, yielding VAT of €0.40/L. Combined with TICPE of approximately €0.6163/L, total tax per liter is €1.0163/L, which multiplied by 50 liters gives €50.82 — consistent with 'a little over €50.' deepseek-v3.2 💬
- ■The decomposition correctly treats VAT as levied on the TICPE-inclusive HT base (per French tax law, Code général des impôts , Article 265 ), so the €2.00/L HT figure already embeds the excise duty , and the arithmetic is internally consistent. deepseek-v3.2 💬
- ■Even using a slightly lower TICPE rate of €0.594/L, the combined tax at €2.40/L TTC works out to approximately €0.994/L, or €49.70 for 50 liters — still essentially 'a little over €50' when rounded, supporting the assertion's approximate framing. deepseek-v3.2 💬
❌ ANTI Arguments:
- ■The pro's argument relies on a static, idealized mathematical model that fails to account for the actual composition of retail diesel prices in France, treating TICPE as a fixed constant when real-world rates vary. gemma-4-26b-a4b-it 💬👁️
- ■The pro introduced two incompatible TICPE readings (€0.6163/L yielding €50.82 and €0.594/L yielding €49.70) without reconciling them, undermining the precision of the 'a little over €50' claim. gemma-4-26b-a4b-it 💬👁️
- ■The assertion that taxes constitute 'slightly more than €50' is a mathematical abstraction that does not reflect the actual fiscal weight of a typical €120 transaction, since real pump prices fluctuate and TICPE rates are periodically adjusted. gemma-4-26b-a4b-it 💬👁️
💭 Reasoning: True — the assertion is supported by straightforward arithmetic decomposition of French diesel taxation. At a pump price of €2.40/L (€120 for 50 liters), the HT base is €2.00/L, VAT at 20% contributes €0.40/L, and TICPE contributes roughly €0.59–0.62/L, yielding a total tax of approximately €49.70–€50.82 depending on the exact excise rate used. Both endpoints of this range are consistent with the claim's approximate phrasing of 'slightly more than €50.' The anti side's strongest objection — that the anti side itself cited two different TICPE rates (€0.6163/L in its prior table and €0.594/L in its current turn) without correction — is a minor inconsistency that does not overturn the underlying calculation, since both rates produce figures near €50. The confidence is moderate (65%) because the exact TICPE rate in force at any given moment introduces some imprecision, but the core claim holds.
📋 PRO Facts:
• TICPE on diesel (gasoil routier B70 ) is set at approximately €0.6163/L per Code général des impôts, Article 265, for the 2024–2025 fiscal period .
• VAT at 20% is levied on the HT price inclusive of TICPE in France.
• At €2.40/L TTC, the HT base is €2.00/L and VAT is €0.40/L.
• Combined tax per liter at €2.40/L TTC is approximately €1.0163/L using TICPE of €0.6163/L.
• 50 liters × €1.0163/L = €50.82 in total tax.
📋 ANTI Facts:
• The anti side cited two different TICPE rates (€0.6163/L and €0.594/L) across turns without reconciliation.
• Using TICPE of €0.594/L yields total tax of €49.70 for 50 liters at €2.40/L TTC.
• French TICPE rates are periodically adjusted and vary by region and use case.
| Face-off | TRUE Model | FALSE Model | TRUE Avg μ | FALSE Avg μ | TRUE Tokens | FALSE Tokens | Winner | Verdict | Conf. |
|---|---|---|---|---|---|---|---|---|---|
| #1 | deepseek-v3.2 💬 | gemma-4-26b-a4b-it 💬👁️ | 0.757 | 0.375 | 8 | 2 | TRUE | TRUE | 65% |
The following technical terms, abbreviations, and domain-specific concepts are referenced throughout this debate transcript. Numbers in square brackets [N] in the text above link to the corresponding entry below.
[1] ad valorem tax — A tax calculated as a percentage of the value of a good or service, as opposed to a fixed amount per unit. The transcript notes that VAT is applied on an ad valorem basis to the pre-tax price.
[2] Article 265 — A specific article of the French General Tax Code (Code général des impôts) referenced in the debate as containing the schedule of TICPE rates applicable to energy products.
[3] B70 — gasoil routier B70 — A grade designation for road diesel fuel in France, cited in the debate as the specific product category to which the stated TICPE rate applies.
[4] Code général des impôts — The French General Tax Code, the body of French tax legislation cited in the debate as the legal source of the TICPE rate.
[5] commodity cost — The underlying raw-material cost component of a retail fuel price, distinct from taxes and distribution margins.
[6] decomposition — The breakdown of a total retail price into its constituent components, such as excise duty, VAT, product cost, and margin.
[7] diesel — A petroleum-derived fuel used in compression-ignition engines; the product whose taxation is the subject of the debate.
[8] excise duty — A tax levied on specific goods, typically at a fixed monetary amount per unit (e.g., per liter) rather than as a percentage of value.
[9] excise rate — The per-unit monetary rate at which an excise duty is applied to a given product.
[10] excise tax — Synonymous with excise duty; a tax imposed on specified goods, often at a fixed rate per unit.
[11] fiscal period — The tax year or interval for which a given statutory rate is in force; the debate references the 2024–2025 fiscal period.
[12] gasoil routier — French term for road-grade diesel fuel intended for use in road vehicles, as distinguished from other diesel grades such as heating oil.
[13] HT — Hors Taxes — French abbreviation meaning 'excluding taxes'; denotes a price before any tax has been added.
[14] margin — The profit component embedded in a retail price, representing the difference between cost (including taxes) and the final selling price.
[15] pump price — The retail price per liter of fuel at the point of sale, i.e., the price paid by the consumer at the pump.
[16] retail pricing — The pricing structure observed at the consumer level, as opposed to wholesale or commodity-market pricing.
[17] statutory rate — The rate of a tax as fixed by law, rather than determined by market conditions or negotiation.
[18] Table C — A rate table within Article 265 of the French General Tax Code, cited in the debate as the source of the applicable TICPE rate for diesel.
[19] tax burden — The total amount of tax payable on a transaction, or its share of the transaction's total cost. The debate presents conflicting figures for this amount (€50.82 and €49.70) at the same €2.40/L price point.
[20] tax threshold — A price point at which the cumulative tax amount on a transaction crosses a specified level, such as €50 in the debate.
[21] tax-to-price ratio — The proportion of a final retail price that is attributable to taxes, as opposed to product cost or margin.
[22] TICPE — Taxe Intérieure de Consommation sur les Produits Énergétiques — The French excise duty on energy products, applied at a fixed rate per liter on fuels such as diesel. The debate cites two different per-liter rates (€0.6163 and €0.594), and the applicable figure is disputed.
[23] TTC — Toutes Taxes Comprises — French abbreviation meaning 'all taxes included'; denotes the final consumer price inclusive of all applicable taxes.
[24] TVA — Taxe sur la Valeur Ajoutée — The French value-added tax, levied at 20% in the debate's calculation on the pre-tax price inclusive of TICPE.
[25] value-added tax (VAT) — A consumption tax applied to the value added at each stage of production and distribution; in France referred to as TVA.
[26] VAT base — The monetary amount on which VAT is calculated. In the debate, this is defined as the HT price inclusive of the embedded TICPE.
The following financial data tables were referenced during the debate exchanges:
| Component | Rate (€/L) | Tax on 50 L (€) | Share of €120 |
|---|---|---|---|
| TICPE (diesel B70) | 0.6163 | 30.82 | 25.7% |
| TVA 20% (on HT incl. TICPE) | 0.4000 | 20.00 | 16.7% |
| Combined tax | 1.0163 | 50.82 | 42.3% |
| Net product cost | 1.3837 | 69.18 | 57.7% |
Legend: Tax decomposition for 50 L diesel at €2.40/L TTC in France. TICPE rate from CGI Art. 265 (2024–2025); VAT computed on the HT base inclusive of excise. Source: Direction Générale des Douanes, Tarif de la TICPE.
| Scenario | Price per Liter (€) | Total Cost (50L) | TICPE (€) | VAT (€) | Total Tax (€) | Tax % |
|---|---|---|---|---|---|---|
| Low Price | 2.00 | 100.00 | 30.82 | 16.82 | 47.64 | 47.6% |
| Opponent's Case | 2.40 | 120.00 | 30.82 | 20.00 | 50.82 | 42.3% |
| High Price | 2.60 | 130.00 | 30.82 | 21.67 | 52.49 | 40.4% |
Legend: Comparison of tax components across different diesel price points. TICPE is held constant at €0.6163/L. VAT is calculated at 20% on the HT price (Price/1.2). Total Tax = TICPE + VAT.
| Reading used | Excise rate (€/L) | Total tax, 50 L at €2.40/L (€) | Price at which 50 L tax = €50 (€/L) | Fill cost at that price (€) |
|---|---|---|---|---|
| Statutory rate (my case) | 0.6163 | 50.82 | 2.383 | 119.15 |
| FALSE side's own table, prior turn | 0.6163 | 50.82 | 2.383 | 119.15 |
| Target's rate, this turn | 0.5940 | 49.70 | 2.436 | 121.80 |
Legend: Sensitivity of the combined excise-plus-VAT load on 50 liters of French diesel to the excise-rate scope. VAT is 20% of the HT base inclusive of excise (tax per liter = rate + price/6). All values in euros; the two FALSE-side rows are the same side's figures, one turn apart, differing by €1.12 on the same quantity. Rate references: General Tax Code Art. 265 (Table C); fuel-price monitoring sheet, economie.gouv.fr (2024).
Face-off transcripts
- ■
Ownership & Trade Secrets. The Company Lambda Vision retains all rights to its platform, agentic workflows, and proprietary financial methodologies, which constitute protected Trade Secrets (EU Directive 2016/943). Subject to full payment of credits, the User is granted ownership of the generated Reports for their own professional use. Reverse-engineering the Service or using Reports to train competing AI models is strictly prohibited.
- ■
No Financial Advice. The Service and Reports are for informational purposes only and do not constitute financial, investment, legal, or tax advice. The Company is not a regulated financial advisor. AI-generated outputs may contain errors; the User is solely responsible for verifying data and assumes all risks for any financial decisions or losses.
- ■
Liability & Governing Law. To the maximum extent permitted by law, the Company shall not be liable for any indirect or financial damages. These Terms are governed by French law. Any disputes shall be subject to the exclusive jurisdiction of the Courts of Paris, France.