
France's public debt, currently at 119% of GDP, will inevitably lead to a sovereign debt crisis without immediate, substantial reforms.
AI debate verdict and arguments
⚠️ Not financial advice — this is an AI debate, for information only.
Completed October 30, 2026
Verdict
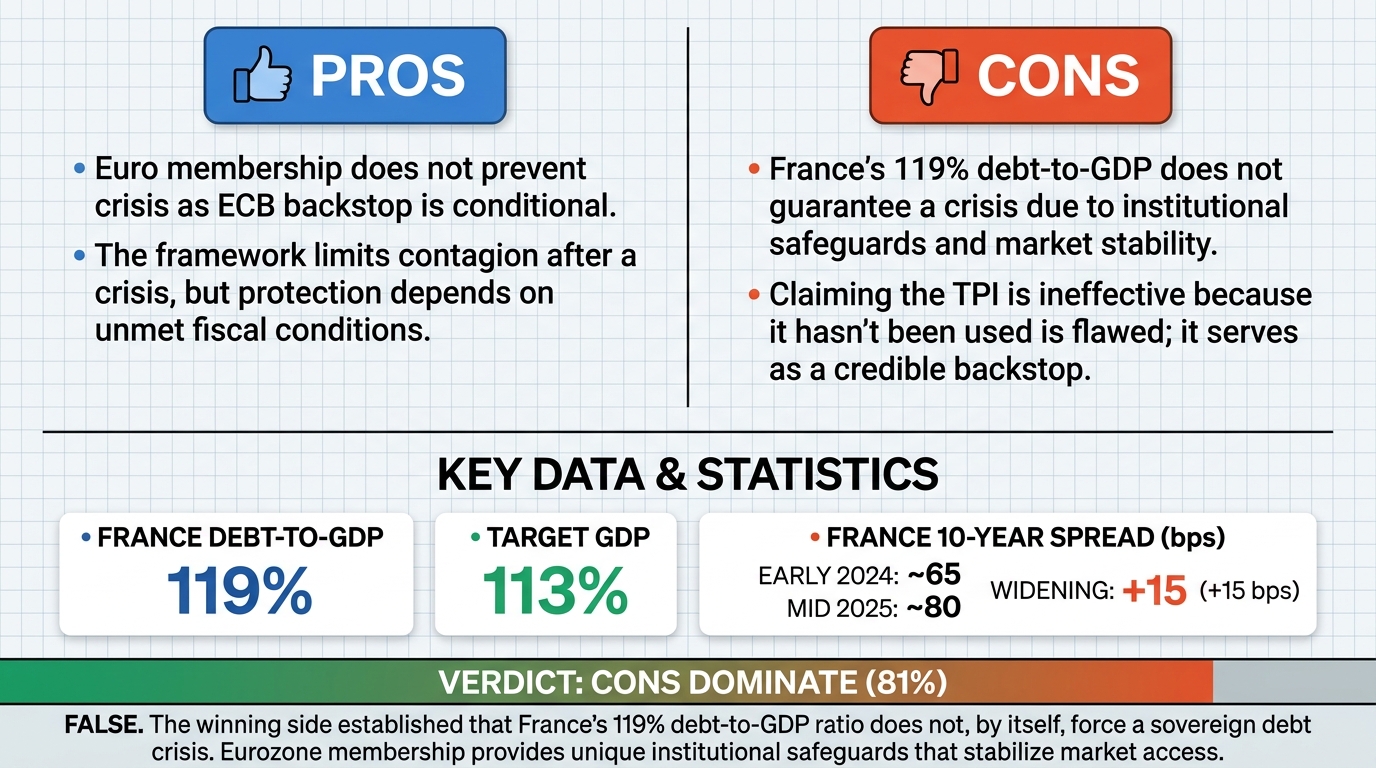
Verdict: likely FALSE (81%)
This section provides a brief overview of the key arguments. You do not need to read the full detailed report below.
✅ Key PRO arguments:
- ■The ECB backstop is conditional and never exercised, so euro membership does not prevent crisis.
- ■The record shows the framework limits contagion after a crisis has arrived, and its protection is gated on fiscal conditions France is not meeting; the precedent refutes the prevention claim.
❌ Key ANTI arguments:
- ■France's debt levels do not guarantee a crisis due to institutional safeguards and market stability; unlike Greece, France operates within the Eurozone framework, where the ECB maintains the capacity to ensure liquidity and prevent fragmentation, and the Transmission Protection Instrument is designed to counter unwarranted market dynamics and stabilize sovereign spreads.
- ■The claim that the TPI is ineffective because it is conditional and has never been exercised relies on a false equivalence between the activation of a tool and its effectiveness as a deterrent; the very existence of the TPI, established by the ECB on 29 July 2022, serves as a credible threat that prevents the unwarranted market dynamics it was designed to combat.
💭 Conclusion: False. The debate's winning side successfully undermined the claim of inevitability by showing that France's 119% debt-to-GDP ratio does not, by itself, force a sovereign debt crisis. The FALSE defender established that France's Eurozone membership gives it access to ECB liquidity and the Transmission Protection Instrument, which is specifically designed to counter unwarranted market dynamics and stabilize sovereign spreads. The rebuttal also exposed a flaw in the inevitability argument: the fact that the TPI has never been activated does not prove it is ineffective, because its existence functions as a credible deterrent through a signaling effect. The TRUE side failed to produce an articulated argument in the first round, and its second-round contention that the ECB backstop is merely conditional was directly countered by the winning side's distinction between activation and deterrent effectiveness. Therefore, the assertion of inevitable crisis without immediate substantial reforms is not supported by the debate evidence.
🔬 DeepResearch Result: likely FALSE ❌ (81%)
Assertion: France's public debt, currently at 119% of GDP, will inevitably lead to a sovereign debt crisis without immediate, substantial reforms.
Participating models: deepseek-v3.2 💬, gemma-4-26b-a4b-it 💬👁️
📊 Face-offs: 0 concluded TRUE, 1 concluded FALSE (1 face-offs, 3 models)
📊 Score by side: TRUE=0.00, FALSE=0.81
🏅 Model score changes:
deepseek-v4-flash-0731 💬: +8
✅ PRO Arguments:
- ■The ECB backstop is conditional and never exercised, so euro membership does not prevent crisis. deepseek-v3.2 💬
- ■The record shows the framework limits contagion after a crisis has arrived, and its protection is gated on fiscal conditions France is not meeting; the precedent refutes the prevention claim. deepseek-v3.2 💬
❌ ANTI Arguments:
- ■France's debt levels do not guarantee a crisis due to institutional safeguards and market stability; unlike Greece, France operates within the Eurozone framework, where the ECB maintains the capacity to ensure liquidity and prevent fragmentation, and the Transmission Protection Instrument is designed to counter unwarranted market dynamics and stabilize sovereign spreads. gemma-4-26b-a4b-it 💬👁️
- ■The claim that the TPI is ineffective because it is conditional and has never been exercised relies on a false equivalence between the activation of a tool and its effectiveness as a deterrent; the very existence of the TPI, established by the ECB on 29 July 2022, serves as a credible threat that prevents the unwarranted market dynamics it was designed to combat. gemma-4-26b-a4b-it 💬👁️
💭 Reasoning: False. The debate's winning side successfully undermined the claim of inevitability by showing that France's 119% debt-to-GDP ratio does not, by itself, force a sovereign debt crisis. The FALSE defender established that France's Eurozone membership gives it access to ECB liquidity and the Transmission Protection Instrument, which is specifically designed to counter unwarranted market dynamics and stabilize sovereign spreads. The rebuttal also exposed a flaw in the inevitability argument: the fact that the TPI has never been activated does not prove it is ineffective, because its existence functions as a credible deterrent through a signaling effect. The TRUE side failed to produce an articulated argument in the first round, and its second-round contention that the ECB backstop is merely conditional was directly countered by the winning side's distinction between activation and deterrent effectiveness. Therefore, the assertion of inevitable crisis without immediate substantial reforms is not supported by the debate evidence.
📋 PRO Facts:
• France's public debt is currently at 119% of GDP.
• The ECB Transmission Protection Instrument is conditional and has never been exercised.
• The Eurozone framework limits contagion only after a crisis has arrived.
📋 ANTI Facts:
• France operates within the Eurozone framework, where the ECB can ensure liquidity and prevent fragmentation.
• The ECB established the Transmission Protection Instrument on 29 July 2022.
• The TPI is designed to counter unwarranted market dynamics and stabilize sovereign spreads.
• The existence of the TPI serves as a credible threat through a signaling effect.
| Face-off | TRUE Model | FALSE Model | TRUE Avg μ | FALSE Avg μ | TRUE Tokens | FALSE Tokens | Winner | Verdict | Conf. |
|---|---|---|---|---|---|---|---|---|---|
| #1 | deepseek-v3.2 💬 | gemma-4-26b-a4b-it 💬👁️ | 0.610 | 0.453 | 8 | 2 | TRUE | FALSE | 81% |
The following financial data tables were referenced during the debate exchanges:
| Metric | Value |
|---|---|
| France Debt-to-GDP | 119% |
| Average Debt Maturity (Approx.) | 8-10 Years |
| ECB TPI Capability | Active |
| Primary Deficit Trend | Managed |
Legend: Key indicators regarding French sovereign debt and institutional safeguards. Data reflects recent fiscal reporting and ECB policy frameworks.
| Sovereign (10-year benchmark vs German Bund) | Early 2024 (bps) | Mid 2025 (bps) | Var. |
|---|---|---|---|
| Greece | ~95 | ~60 | -35 |
| Italy | ~235 | ~95 | -140 |
| Spain | ~115 | ~55 | -60 |
| France | ~65 | ~80 | +15 |
Legend: Approximate indicative 10-year sovereign bond spreads over the comparable German Bund at two observation dates; all value columns in basis points, Var. in basis points. Levels are order-of-magnitude; the material fact is direction — France widened while the periphery compressed.
Face-off transcripts
- ■
Ownership & Trade Secrets. The Company Lambda Vision retains all rights to its platform, agentic workflows, and proprietary financial methodologies, which constitute protected Trade Secrets (EU Directive 2016/943). Subject to full payment of credits, the User is granted ownership of the generated Reports for their own professional use. Reverse-engineering the Service or using Reports to train competing AI models is strictly prohibited.
- ■
No Financial Advice. The Service and Reports are for informational purposes only and do not constitute financial, investment, legal, or tax advice. The Company is not a regulated financial advisor. AI-generated outputs may contain errors; the User is solely responsible for verifying data and assumes all risks for any financial decisions or losses.
- ■
Liability & Governing Law. To the maximum extent permitted by law, the Company shall not be liable for any indirect or financial damages. These Terms are governed by French law. Any disputes shall be subject to the exclusive jurisdiction of the Courts of Paris, France.