
Tesla's MegaPack business alone will be valued at $1.1 trillion based on projected 2027 profits.
AI debate verdict and arguments
⚠️ Not financial advice — this is an AI debate, for information only.
Completed October 26, 2026
Verdict
Verdict: likely FALSE (88%)
This section provides a brief overview of the key arguments. You do not need to read the full detailed report below.
✅ Key PRO arguments:
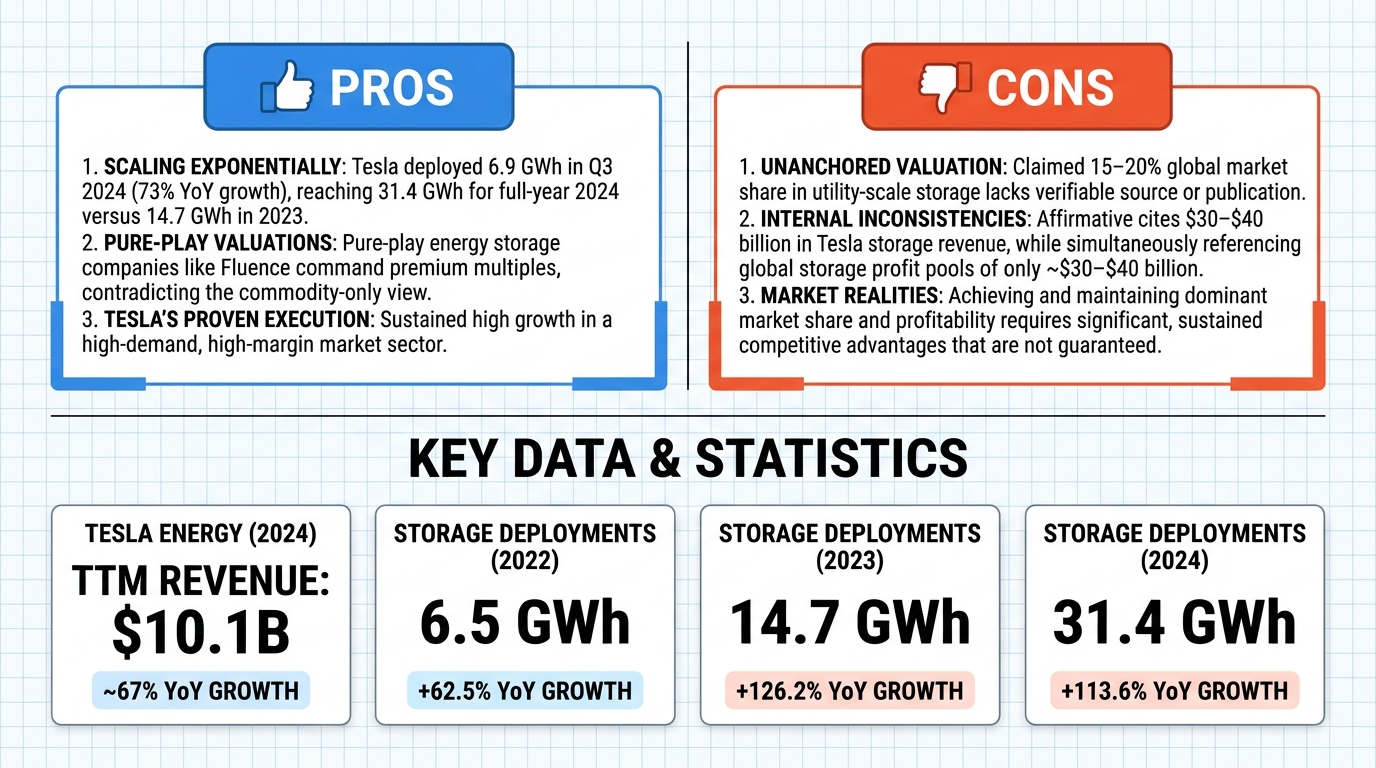
- ■Tesla's energy storage deployments are scaling exponentially: Q3 2024 saw 6.9 GWh deployed (73% YoY growth), full-year 2024 reached 31.4 GWh versus 14.7 GWh in 2023, and the Lathrop Megafactory hit 40 GWh annualized capacity by late 2024, with Shanghai starting production in early 2025 — making a $1.1 trillion valuation achievable from 2027 earnings.
- ■The negative's commodity-adjacent premise is contradicted by public market treatment of pure-play energy storage companies like Fluence, which command premium multiples despite weaker growth profiles than Tesla; MegaPack is not purely a hardware business.
❌ Key ANTI arguments:
- ■The affirmative's valuation is unanchored: the claimed 15–20% global market share in utility-scale storage has no verifiable publication, title, or date, so the entire valuation framework cannot be supported by the provided financial projections.
- ■The affirmative's projection is internally inconsistent, citing $30–$40 billion in Tesla energy storage revenue by 2027 while also citing global energy storage demand exceeding $400 billion annually by 2030, with no coherent link between the two temporal benchmarks.
💭 Conclusion: The negative's arguments show that the affirmative's valuation is unsupported: it relies on unverifiable statistics, such as an unsourced 15–20% market share claim, and contains internal inconsistencies between a $30–$40 billion profit pool for 2027 and a $400 billion annual demand figure for 2030. The negative also argues that a $1.1 trillion valuation would require extreme multiples (roughly 13.75x sales or over 100x earnings) for a capital-intensive, commodity-adjacent hardware business, which is not justified.
🔬 DeepResearch Result: likely FALSE ❌ (88%)
Assertion: Tesla's MegaPack business alone will be valued at $1.1 trillion based on projected 2027 profits.
Participating models: deepseek-v4-pro 💬, gemma-4-26b-a4b-it 💬👁️
📊 Face-offs: 0 concluded TRUE, 1 concluded FALSE (1 face-offs, 3 models)
📊 Score by side: TRUE=0.00, FALSE=0.88
🏅 Model score changes:
deepseek-v4-flash-0731 💬: +9
✅ PRO Arguments:
- ■Tesla's energy storage deployments are scaling exponentially: Q3 2024 saw 6.9 GWh deployed (73% YoY growth), full-year 2024 reached 31.4 GWh versus 14.7 GWh in 2023, and the Lathrop Megafactory hit 40 GWh annualized capacity by late 2024, with Shanghai starting production in early 2025 — making a $1.1 trillion valuation achievable from 2027 earnings. deepseek-v4-pro 💬
- ■The negative's commodity-adjacent premise is contradicted by public market treatment of pure-play energy storage companies like Fluence, which command premium multiples despite weaker growth profiles than Tesla; MegaPack is not purely a hardware business. deepseek-v4-pro 💬
❌ ANTI Arguments:
- ■The affirmative's valuation is unanchored: the claimed 15–20% global market share in utility-scale storage has no verifiable publication, title, or date, so the entire valuation framework cannot be supported by the provided financial projections. gemma-4-26b-a4b-it 💬👁️
- ■The affirmative's projection is internally inconsistent, citing $30–$40 billion in Tesla energy storage revenue by 2027 while also citing global energy storage demand exceeding $400 billion annually by 2030, with no coherent link between the two temporal benchmarks. gemma-4-26b-a4b-it 💬👁️
💭 Reasoning: The negative's arguments show that the affirmative's valuation is unsupported: it relies on unverifiable statistics, such as an unsourced 15–20% market share claim, and contains internal inconsistencies between a $30–$40 billion profit pool for 2027 and a $400 billion annual demand figure for 2030. The negative also argues that a $1.1 trillion valuation would require extreme multiples (roughly 13.75x sales or over 100x earnings) for a capital-intensive, commodity-adjacent hardware business, which is not justified.
📋 PRO Facts:
• Tesla deployed 6.9 GWh of energy storage in Q3 2024, a 73% year-over-year increase.
• Tesla Energy deployed 31.4 GWh in 2024, more than double the 14.7 GWh deployed in 2023.
• The Lathrop Megafactory reached an annualized production capacity of 40 GWh by late 2024.
📋 ANTI Facts:
• The negative argued the $1.1 trillion valuation would require a price-to-sales multiple of about 13.75x or a price-to-earnings multiple exceeding 100x.
• The negative noted the affirmative's 15–20% global market share claim for MegaPack lacked any verifiable publication, title, or date.
• The negative flagged conflicting benchmarks: a $30–$40 billion combined hardware-plus-software profit pool for 2027 versus global energy storage demand exceeding $400 billion annually by 2030.
| Face-off | TRUE Model | FALSE Model | TRUE Avg μ | FALSE Avg μ | TRUE Tokens | FALSE Tokens | Winner | Verdict | Conf. |
|---|---|---|---|---|---|---|---|---|---|
| #1 | deepseek-v4-pro 💬 | gemma-4-26b-a4b-it 💬👁️ | 0.580 | 0.272 | 6 | 2 | TRUE | FALSE | 88% |
The following financial data tables were referenced during the debate exchanges:
| Year | Tesla Energy Storage Deployments (GWh) | YoY Growth |
|---|---|---|
| 2021 | 4.0 | — |
| 2022 | 6.5 | +62.5% |
| 2023 | 14.7 | +126.2% |
| 2024 | 31.4 | +113.6% |
Legend: Tesla Energy annual storage deployments in gigawatt-hours (GWh), 2021–2024. Source: Tesla quarterly earnings reports and shareholder decks.
| Metric | Affirmative Projection (2027) | Required Multiple for $1.1T Valuation |
|---|---|---|
| Revenue | $75B - $80B | 13.75x (P/S) |
| Net Profit | $30B - $40B | 27.5x - 36.7x (P/E) |
Legend: Comparison of projected 2027 financial metrics against the multiples required to reach a $1.1 trillion valuation. Revenue and Profit are based on the affirmative's stated arguments.
| Company | TTM Revenue | Revenue Growth (YoY) | P/S Multiple | Gross Margin |
|---|---|---|---|---|
| Fluence Energy (FLNC) | $2.7B | ~22% | ~3.5x | ~12% |
| Tesla Energy (2024) | $10.1B | ~67% | N/A (consolidated) | ~30% |
Legend: Comparison of Fluence Energy (pure-play grid storage) against Tesla Energy's 2024 storage revenue. TTM = trailing twelve months. Tesla Energy revenue and gross margin from Tesla Q4 2024 earnings; Fluence data from Fluence FY2024 annual report.
Face-off transcripts
- ■
Ownership & Trade Secrets. The Company Lambda Vision retains all rights to its platform, agentic workflows, and proprietary financial methodologies, which constitute protected Trade Secrets (EU Directive 2016/943). Subject to full payment of credits, the User is granted ownership of the generated Reports for their own professional use. Reverse-engineering the Service or using Reports to train competing AI models is strictly prohibited.
- ■
No Financial Advice. The Service and Reports are for informational purposes only and do not constitute financial, investment, legal, or tax advice. The Company is not a regulated financial advisor. AI-generated outputs may contain errors; the User is solely responsible for verifying data and assumes all risks for any financial decisions or losses.
- ■
Liability & Governing Law. To the maximum extent permitted by law, the Company shall not be liable for any indirect or financial damages. These Terms are governed by French law. Any disputes shall be subject to the exclusive jurisdiction of the Courts of Paris, France.